Caregiving Support for Adult Family Members May Influence Midterm Voters, AARP Survey Finds

Industry overview
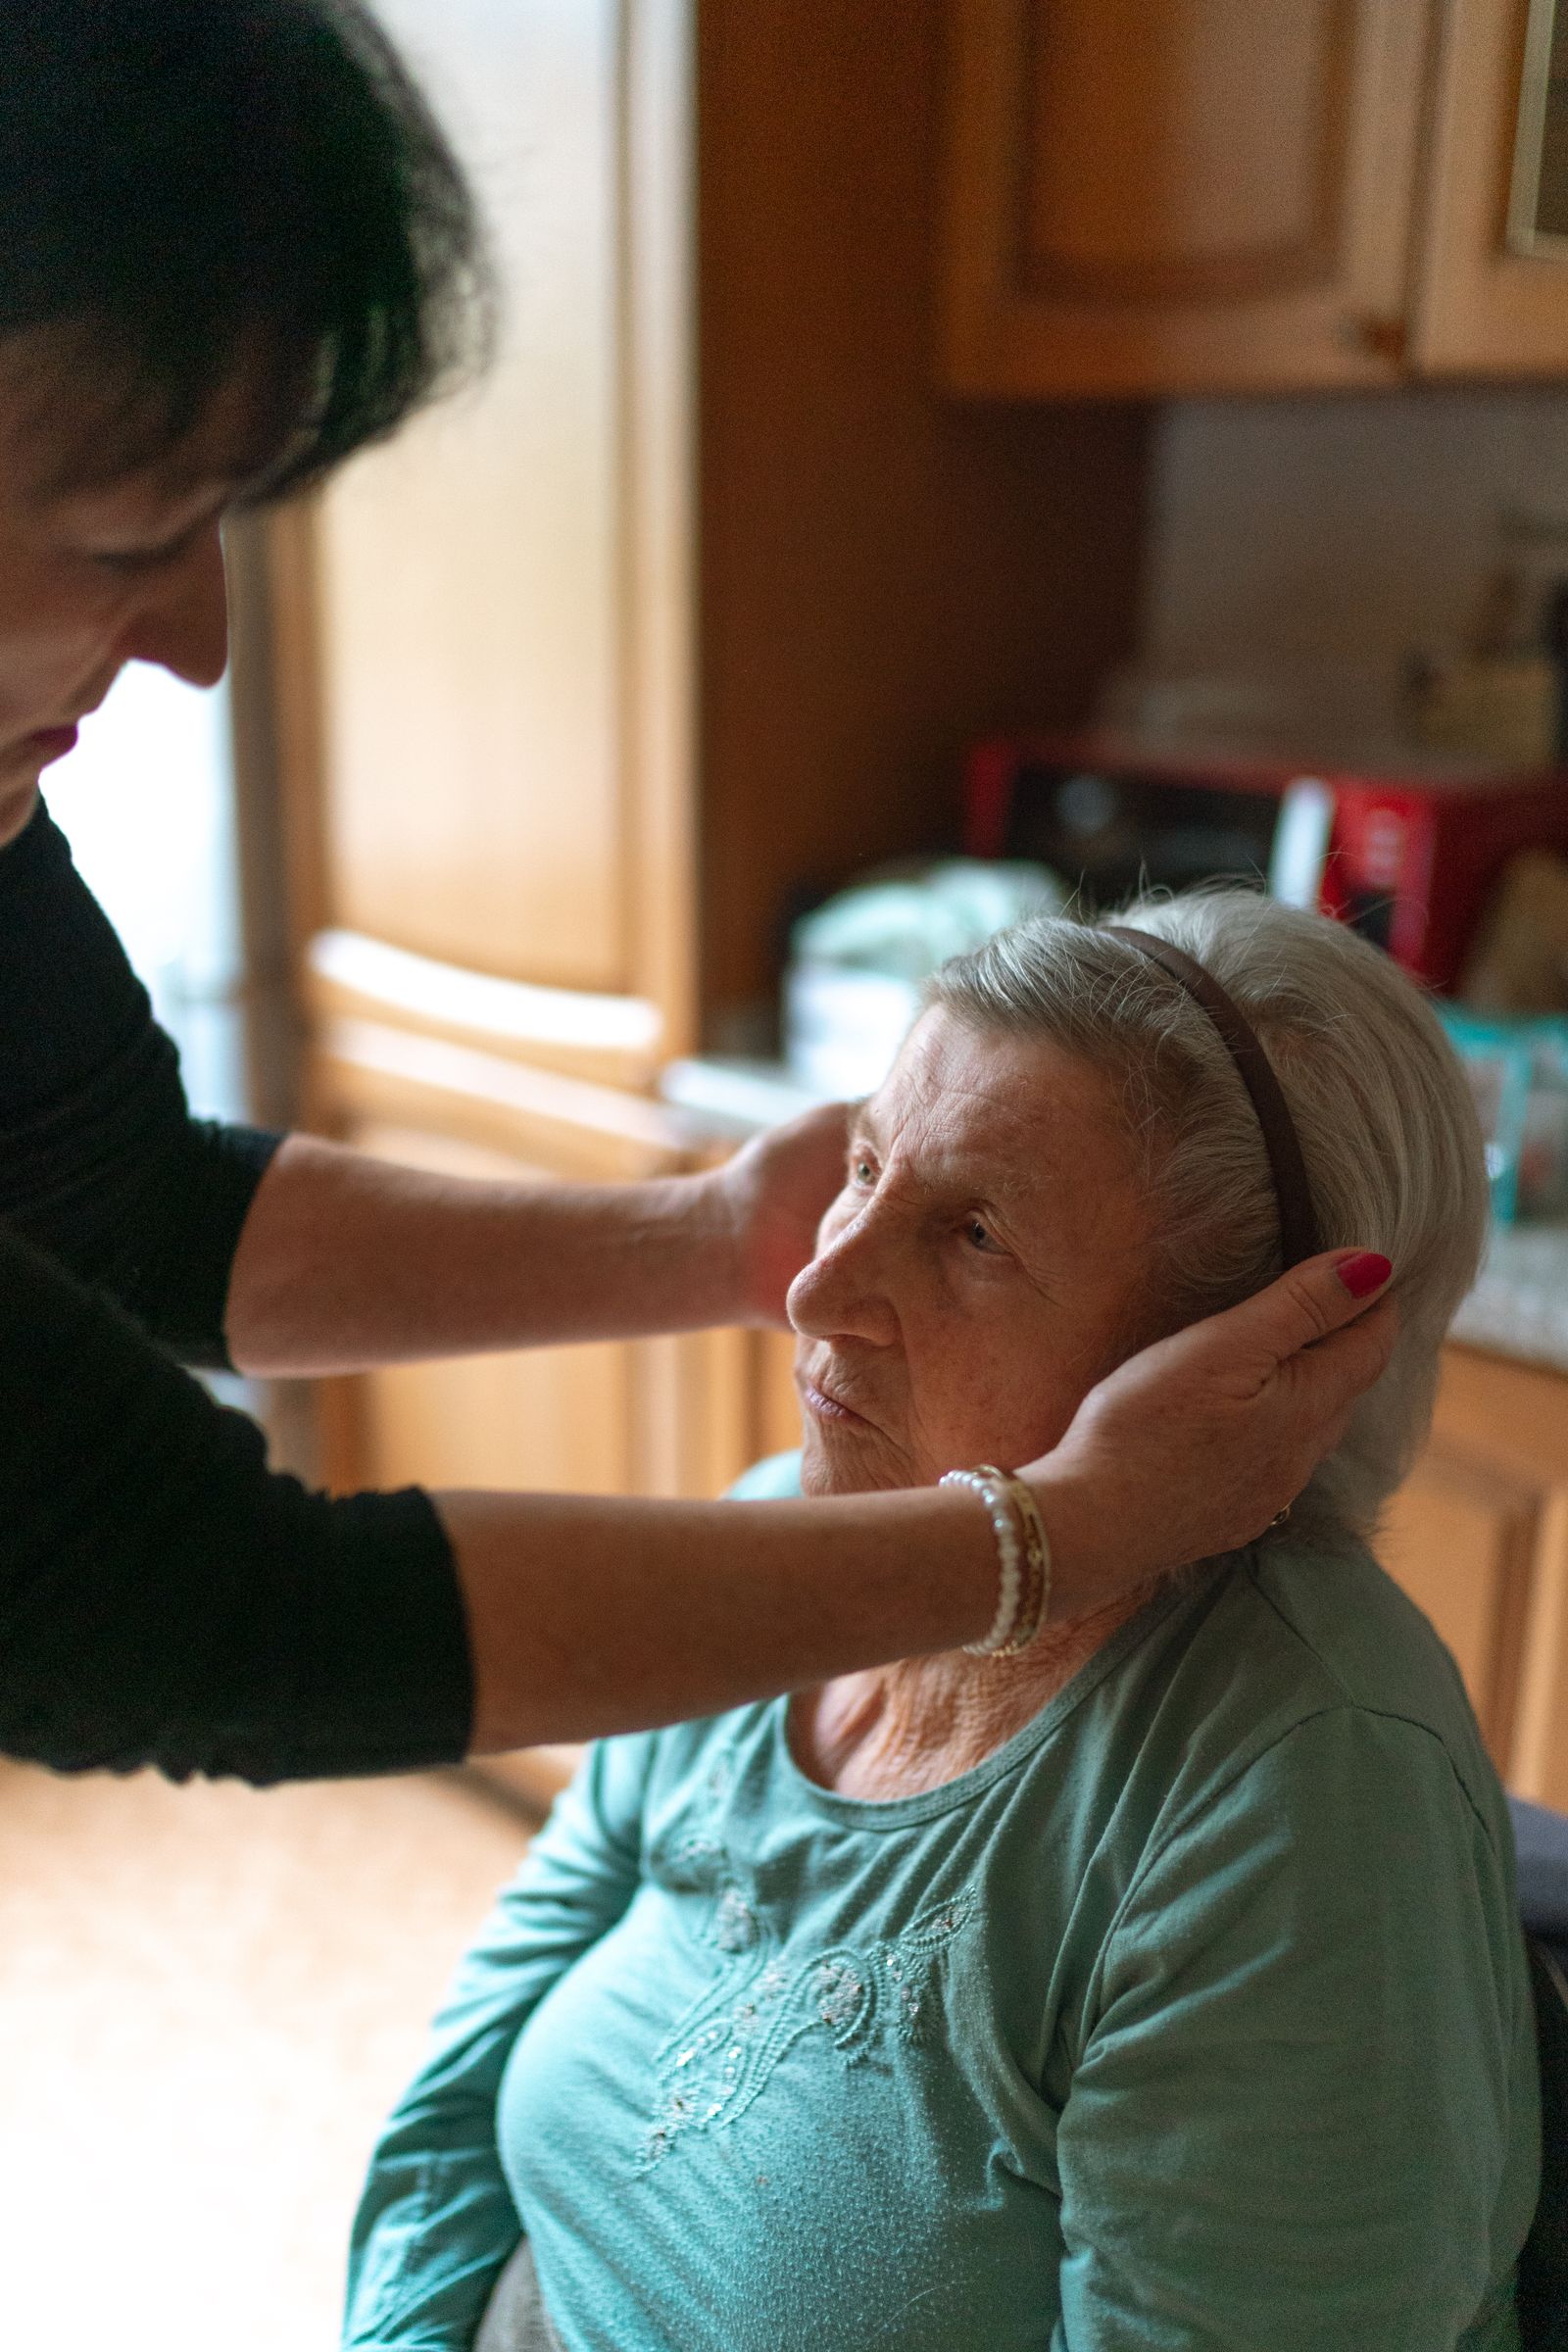
For millions of American families, caring for a loved one is no longer just a personal duty — it is a growing affordability problem, and it is now showing up in the 2026 midterm elections. About 59 million Americans look after an adult family member, neighbor or friend, according to a recent AARP report. AARP is a nonprofit, nonpartisan group that advocates for people age 50 and older. An Edward Jones study found that Americans caring for aging relatives spend an average of $8,737 a year out of pocket, with their retirement savings and careers taking the hit.
A new AARP survey suggests the issue could move votes. In 43 competitive congressional districts, most likely voters age 50 and older said they would be more inclined to back candidates who support policies for unpaid caregivers. Because voters 50 and up form one of the most influential voting blocs, that support could decide tight races. Among those older voters, 77% said they would be more likely to vote for a candidate who favored a tax credit for unpaid family caregivers who help pay for a loved one’s care, and 75% said the same about a candidate who backed help for caregivers keeping loved ones at home. Fabrizio Ward and Impact Research ran the survey for AARP, interviewing 1,368 likely voters age 18 and older — including 848 age 50 and older — from Oct. 1 to 5. The margin of error for the full sample was plus or minus 2.7 percentage points, and the data was weighted to reflect the voting population of the targeted districts. Voters 50 and above “are going to be the deciders in the election,” said Matt Hogan, a partner at Impact Research, a public opinion research and consulting firm. “So for candidates looking to win over this critical voting bloc, a focus on helping caregivers would go a long way in helping them make inroads.”
Brittney Saunders Graves with her mother, Tracey Saunders, in the hospital in 2020.
Courtesy: Brittney Saunders Graves
The strain shows up in household budgets. Brittney Saunders Graves, a 33-year-old part-time counselor in Temple, Texas, is the main family caregiver for her 62-year-old mother, Tracey Saunders, who suffered a debilitating stroke in 2020. Graves, a U.S. Army veteran who has also survived a stroke, spends about $600 a month on her mother’s care, covering transportation, copays and medications. “After we set aside the necessities, leaving out medication [and] doctor’s appointments, she only has around $400 to cover food,” Graves said.
The damage goes beyond monthly bills. Caregivers are more likely than non-caregivers to hold fewer financial assets and to struggle with debt, according to the Employee Benefit Research Institute’s 2026 Retirement Confidence Survey. About 34% of caregivers reported less than $10,000 in savings and investments, compared with 25% of non-caregivers, and 69% said debt is a problem, versus 57% of non-caregivers. Those pressures make it harder to build savings, cover household expenses and prepare for retirement.
The squeeze is sharpest for the so-called sandwich generation — people supporting aging parents while also raising children or carrying other family responsibilities, said Keesha Middlemass, a political science professor at Howard University. “The sandwich generation is only going to get larger” as the population ages and lifespans increase, she said. Sarah Smitley, a 50-year-old in Sylvania, Ohio, cares for her 20-year-old daughter, who has autism, while also helping her aging parents. Smitley works as a family navigator for a nonprofit that supports people with mental illness, and she wants political leaders to grasp the affordability crunch caregivers face. “Maybe we can’t take off time, or we’ve run out of vacation pay, or we know medical costs are high even with insurance and just out of pocket that it’s not easy to come up with another $50,” she said.
Medicaid cuts in President Donald Trump’s “big beautiful bill” are set to take effect in January, and without government help, unpaid family caregivers who often pay their loved ones’ expenses would face still greater hardship, Middlemass said. “The future cuts, actually, that are going to come to Medicaid and Medicare in 2027 are going to be devastating for those in the lower incomes, but also workers that are in the care economy,” she said.

Paula Bussard, a 71-year-old retiree in Carlisle, Pennsylvania, worries the cuts will leave fewer doctors, home health agencies and medical equipment providers willing to accept Medicaid. She cares for her 42-year-old son, Alex, who has complex medical needs after surviving a brain tumor and a brain hemorrhage, and the family already spends $5,000 to $7,000 a year caring for him at home, including accommodations and supplies Medicaid does not cover. “Political candidates need to know that every human being deserves dignity, respect and health care,” Bussard said, adding that Medicaid is crucial for millions of Americans who cannot work and “helps their families take care of them in the home.”
Paula Bussard with her son Alex Bussard in 2025.
Courtesy: Paula Bussard
Even so, families already stretched by caregiving costs say campaign promises do not necessarily inspire confidence that real help is coming. “When you look at, okay, this is being advertised, but then you peel it back, it’s like, will this happen? Will this happen?” Graves said.
Industry overview based on CNBC.
What it means for investors
Caregiving has become a swing issue in 43 competitive congressional districts, and the voters who care most about it — Americans 50 and older — are among the most reliable voters in midterm elections. That makes caregiver tax credits and home-care support live policy risks for investors to track after the election: if they advance, they could lift demand for home health, home-care services and the companies that supply them, while easing the out-of-pocket burden that now falls on families. The other side of the ledger is Medicaid. Cuts taking effect in January, with more to Medicaid and Medicare expected in 2027, threaten providers that depend on public reimbursement — fewer doctors, agencies and equipment suppliers accepting Medicaid means thinner volumes and tougher economics for home-health and managed-care businesses exposed to those programs. The care economy also feeds into the broader market: when caregivers cut hours, drain savings or delay retirement, consumer spending and labor supply feel it. For investors, the signal to watch is not just who wins, but whether the winning candidates follow through on caregiver pledges — the families in this story are openly skeptical that they will.
What it means for employees
This story is directly about workers. Caregiving collides with jobs: the caregivers in the article juggle part-time work, burn through vacation pay, and see their careers and retirement savings take the hit — the Edward Jones study puts the average out-of-pocket cost at $8,737 a year, and the EBRI survey shows caregivers far more likely to carry debt and hold under $10,000 in savings and investments. For employers, that translates into retention and productivity risk among the sandwich generation, a group that will only grow as the population ages. It also matters for workers in the care economy itself: Middlemass warns that the Medicaid and Medicare cuts coming in 2027 will be “devastating” for lower-income people and care workers. Companies that offer flexible schedules, caregiver leave and benefits that ease these costs have a real edge in keeping experienced staff.
What it means for customers
For families who buy care — or pay for it out of pocket — the message is that costs are high and help is uncertain. The average caregiver already spends $8,737 a year, and families like the Bussards pay $5,000 to $7,000 a year for care at home that Medicaid does not cover. The January Medicaid cuts, and the further cuts expected in 2027, could make it harder to find doctors, home health agencies and equipment providers that accept Medicaid, pushing more of the cost onto families. The proposals voters favor — a tax credit for unpaid caregivers and support to keep loved ones at home — could ease that burden if they become law, but as Graves put it, families are waiting to see whether campaign promises turn into anything real. Until then, households should budget for care costs as a long-term expense, not a temporary one.
Note: Investment calculations and projections are for illustrative purposes only. Market conditions change frequently. Consult a qualified financial advisor before making investment decisions.


